Foreign-owned companies operating in South Korea do not automatically need one universal policy called “business liability insurance” simply because their shareholders are overseas. The real question is more specific: which Korean insurance requirements apply to your employees, vehicles, premises, data, products, contracts, and industry?
For many companies, the answer is a mixture of statutory insurance and optional commercial coverage. Industrial accident insurance may apply when you employ workers. Company vehicles trigger compulsory motor insurance. Certain facilities require disaster liability insurance. Some businesses handling large volumes of personal information must maintain insurance, mutual-aid coverage, reserves, or a permitted combination of those measures.
On top of those legal requirements, a foreign-owned subsidiary or Korean branch may choose commercial general liability, product liability, professional indemnity, employer’s liability, cyber, directors and officers insurance, or other cover because its contracts and actual exposures make them sensible. The important part is not buying the longest menu of policies. It is matching each policy to a real Korean exposure.
Table of Contents
Start with the entity you are insuring
A foreign investor can operate in Korea through different structures, and that distinction matters before an insurance program is designed.
Invest Korea’s guidance on how foreigners can start a business in Korea distinguishes a foreign-invested Korean company from a domestic branch of a foreign corporation. A foreign-invested company is a Korean domestic corporation, while a branch remains part of the foreign corporation. Invest Korea’s comparison also notes that a branch’s legal liability can extend to its head office, whereas a local corporation is legally independent.
That difference can affect who should appear as the named insured, whether the overseas parent needs to be included, how intercompany services are treated, and whether a claim arising in Korea could reach the foreign head office. Guarantees, contracts, statutory duties, corporate-group relationships, and case-specific liability rules can still change the outcome, so entity structure should be reviewed rather than treated as an automatic liability shield.
If you are still establishing the operation, Invest Korea also explains that foreign-invested companies generally follow Korean incorporation procedures with additional foreign-investment notification and registration steps. Insurance should therefore be coordinated with the actual Korean entity being incorporated, not merely purchased in the overseas parent’s name.
Which liability-related insurance can be mandatory in Korea?
There is no single checklist that applies identically to every company. Requirements can arise from the company’s workforce, property, vehicles, data processing, licensing status, or industry.
| Exposure | Possible Korean requirement | What to check |
|---|---|---|
| Employees | Industrial accident compensation insurance | Whether the workplace falls within the statutory coverage rules or an exclusion |
| Company-owned vehicles | Compulsory motor liability coverage | Vehicles registered or operated by the company and required liability limits |
| Certain premises or facilities | Disaster liability insurance or mutual aid | Whether the facility is one of the prescribed categories |
| Large-scale personal data processing | Insurance, mutual aid, reserves, or an allowed combination | Revenue, number of data subjects, statutory minimum amount, and exemptions |
| Regulated activities | Industry-specific compulsory insurance | Licenses, permits, professional rules, contracts, and sector legislation |
Industrial accident compensation insurance
Korea’s Industrial Accident Compensation Insurance Act applies broadly to businesses and workplaces that use workers, subject to specified statutory exclusions. The current Article 6 coverage rule should therefore be one of the first checks for a foreign-owned company hiring employees in Korea.
This statutory system should not be confused with optional employer’s liability coverage. A commercial employer’s liability policy may address certain employer liabilities beyond amounts handled by the statutory industrial accident system, depending on its wording. It does not simply replace the statutory program.
Employment documentation also matters when building the company’s risk file. For related operational context, see this site’s guide to employment contracts in Korea.
Company vehicle insurance
If the Korean company owns vehicles, motor liability is a separate compliance issue rather than something that should be assumed to sit inside a general business liability policy. Korea’s Act on Guarantee of Compensation for Loss Caused by Automobile requires automobile owners to maintain prescribed liability coverage for death or bodily injury and also addresses property-damage coverage.
A company operating delivery vehicles, executive cars, service vans, or other registered vehicles should therefore maintain an accurate vehicle schedule and verify the appropriate compulsory and optional motor coverage separately. The site’s car insurance in Korea for foreigners guide provides additional background on the local motor-insurance environment.
Disaster liability insurance for specified facilities
Some premises trigger another layer of mandatory liability insurance. The Korean Ministry of the Interior and Safety explains that prescribed disaster-vulnerable facilities must carry disaster liability insurance covering harm to third parties from events such as fire, collapse, or explosion.
The ministry’s current disaster liability insurance guidance identifies 20 facility categories, including certain tourist accommodation facilities, logistics warehouses, museums, art galleries, restaurants, funeral halls, gas stations, passenger terminals, exhibition facilities, and rural lodging businesses.
This is a good example of why “we are only an office” and “we are a foreign company” are not useful insurance classifications by themselves. A foreign-owned hospitality business, logistics facility, manufacturer, retailer, and software office can face very different mandatory-insurance rules.
Personal information liability requirements
Cyber insurance is often discussed as an optional technology purchase, but Korean personal-information law can create a separate financial-responsibility requirement for qualifying personal information controllers.
Under Article 39-7 of the Personal Information Protection Act, qualifying controllers must take measures such as purchasing insurance, joining a mutual-aid arrangement, or accumulating reserves to support their liability for damages.
As of September 2026, the Enforcement Decree’s Article 48-7 generally brings a controller within the requirement when both relevant thresholds are met: prior-year revenue of at least KRW 1 billion and an average of at least 10,000 covered data subjects during the specified measurement period. Exceptions and detailed definitions apply.
The minimum insurance or reserve requirement then varies according to both revenue and the number of data subjects. Under the current Appendix 1-4 structure, amounts run from KRW 50 million at the lower applicable tier to KRW 1 billion for the highest combination shown in the table.
A company should not treat a generic international cyber policy as automatic proof of compliance. Confirm whether the Korean entity is the insured party, whether the wording covers the liabilities contemplated by Korean law, and whether the insured limit or reserve arrangement satisfies the applicable Korean threshold.
What optional liability insurance should a foreign-owned company consider?
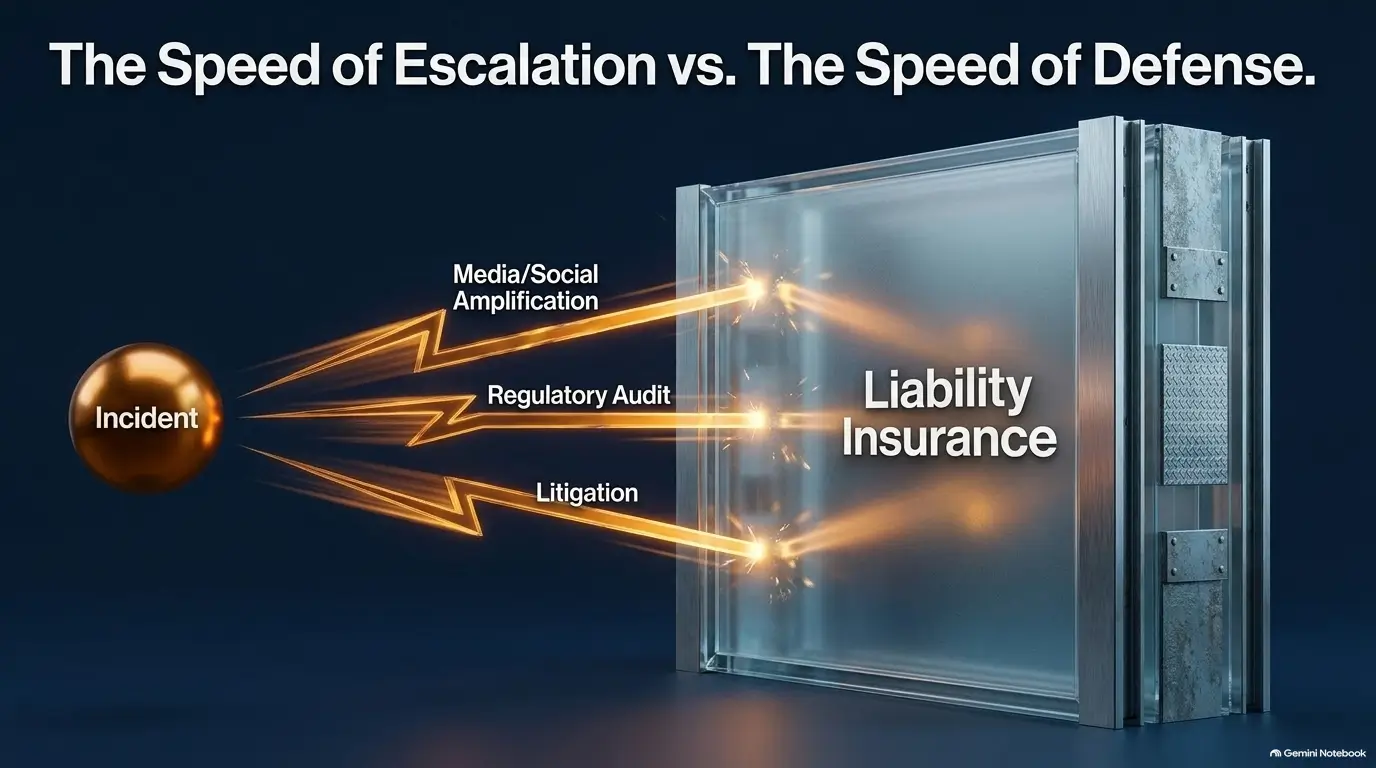
After statutory requirements are separated out, the next layer is ordinary commercial risk. The following policies are not interchangeable, even though they are sometimes bundled or discussed under the broad label of business liability insurance.
Commercial general liability
Commercial general liability, often called CGL or general liability, is designed primarily around third-party bodily injury and property-damage exposures arising from business operations or premises, subject to the policy wording.
A Korean office receiving customers, a showroom, a warehouse, a retail operation, a contractor, or a company running events may have obvious premises and operational exposures. Even an office with relatively little physical risk may face lease provisions or customer contracts requiring specified limits and evidence of insurance.
Pay close attention to contractual liability exclusions. Agreeing in a customer contract to indemnify the customer does not necessarily mean the entire contractual promise is insured.
Product liability
Manufacturers, importers, distributors, component suppliers, consumer brands, and businesses selling Korean-made products overseas should evaluate product liability separately from premises liability.
Territory matters. A Korean company exporting into the United States, United Kingdom, European Union, or other markets should confirm whether the policy’s territorial and jurisdiction provisions match where products are sold and where claims could be brought. Product recall costs also should not be assumed to be included merely because product liability is insured.
Professional indemnity or errors and omissions insurance
A software developer, consultant, designer, engineer, marketing agency, technology integrator, or professional-services company can cause a customer substantial financial loss without causing physical injury or physical property damage.
That is where professional indemnity or errors and omissions coverage may become more relevant than traditional general liability. Check the policy definition of professional services, exclusions for contractual guarantees, intellectual-property provisions, cyber overlap, and whether defense costs reduce the liability limit.
Directors and officers insurance
Foreign-appointed directors, Korean executives, and local officers may face claims connected with their management decisions. Directors and officers insurance, commonly called D&O, can therefore be important where a Korean operation has an active board, investors, substantial employees, regulatory exposure, financing, or complex corporate relationships.
The insured-person definition should reflect the actual Korean governance structure. A parent company’s D&O policy should also be checked to determine whether the Korean entity and its directors fall within the policy’s subsidiary definition and territorial scope.
Cyber and privacy liability
Cyber coverage can be relevant even when the company does not cross Korea’s statutory insurance-or-reserve threshold. A smaller business can still suffer ransomware, data restoration costs, business interruption, incident-response expenses, privacy claims, or contractual disputes following a security event.
For companies subject to Korea’s statutory personal-information financial-responsibility rule, the compliance question and the broader cyber-risk question should be analyzed together but not confused. A policy can be commercially useful without necessarily satisfying a statutory requirement, and a minimum statutory arrangement may still provide less protection than the company’s actual exposure.
Do not assume the overseas parent policy automatically solves the Korean problem
This is one of the most important issues for multinational groups.
A parent company may already have a global liability, D&O, cyber, property, or professional indemnity program. That does not mean the Korean subsidiary should simply rely on a certificate issued overseas.
Korea’s Insurance Business Act Article 3 generally restricts entering into an insurance contract with a person that is not an authorized insurance company, subject to exceptions prescribed by Presidential Decree. The Enforcement Decree lists circumstances in which contracts with foreign insurers are permitted, including specified categories and other defined exceptions.
For that reason, multinational companies should ask a Korean-licensed broker or qualified adviser whether they need a locally issued policy, how the Korean policy should coordinate with the group’s master program, and whether a mandatory Korean policy requires locally compliant wording or evidence of insurance.
Do not assume that a foreign master policy, a contractual indemnity from the parent, or a large global aggregate limit is automatically equivalent to Korean statutory compliance.
How much liability insurance should the company buy?
Outside statutory minimums, there is no meaningful universal number for every foreign-owned company. A sensible limit should be driven by the loss scenarios the company could realistically face and by contractual requirements.
When setting limits, review at least the following:
- Maximum liability limits required by major customer contracts.
- Lease requirements for offices, factories, warehouses, and retail premises.
- Number of employees and the nature of their work.
- Maximum number of customers, visitors, or members of the public at the premises.
- Annual revenue and the value of the largest customer relationship.
- Products sold, units shipped, and export destinations.
- Largest realistic product, professional-services, cyber, or premises claim.
- Personal information volumes and applicable Korean privacy requirements.
- Existing parent-company master policies and their local subsidiary provisions.
Contract review is particularly important. A customer may require a KRW, USD, or other currency limit that is much higher than what the company would otherwise purchase. The contract might also request additional-insured status, waiver of subrogation, particular policy wording, or evidence of insurance before work begins.
What affects the premium?
Quoting business liability insurance in Korea generally requires much more than the company’s name and headcount. The insurer is trying to understand the frequency and severity of the exposure.
- Industry: an office-based consulting company presents a different risk from a chemical manufacturer, construction contractor, restaurant, or logistics warehouse.
- Revenue: turnover often acts as an exposure measure for general, professional, and product liability underwriting.
- Payroll and employees: these matter especially for workplace and employer-related risks.
- Premises: location, size, occupancy, public access, fire protection, and the activity conducted there can matter.
- Products: product type, safety characteristics, manufacturing controls, unit volume, and destination countries affect product risk.
- Contracts: indemnities, warranties, service commitments, and liability caps can materially change exposure.
- Claims history: insurers normally ask about previous incidents, claims, and circumstances that could become claims.
- Limits and deductibles: higher limits generally increase insurer exposure, while the policy’s retained amount changes how risk is shared.
- Territory: companies serving customers or exporting products outside Korea may need broader territorial and jurisdictional protection.
Because those variables differ so widely, a generic premium range can be more misleading than useful. A small Seoul consulting office and a foreign-owned manufacturing plant with exports to North America are not variations of the same insurance risk.
Documents to prepare before requesting quotes
Preparing a clean underwriting package can reduce repeated questions and make competing quotations easier to compare.
- Korean business registration certificate and basic corporate information.
- Explanation of whether the entity is a Korean subsidiary, branch, or another structure.
- Description of operations in Korea.
- Current and projected annual revenue, including revenue by major business activity where relevant.
- Employee count and payroll information where requested.
- Address, floor area, occupancy, and use of each location.
- Product descriptions, annual sales, export countries, and distribution arrangements for product risks.
- Major customer contracts containing insurance or indemnification clauses.
- Vehicle schedule where company vehicles are involved.
- Personal-data volumes and processing activities where cyber or privacy obligations are relevant.
- Three to five years of claims history if available.
- Copies or summaries of the foreign parent’s existing global insurance policies.
Policy wording matters more than the label on the certificate
Two policies both described as “liability insurance” can behave very differently when a claim arrives. Before choosing primarily by premium, examine the operative wording.
- Occurrence versus claims-made: identify what event must happen during the policy period to trigger coverage.
- Retroactive date: this can be critical for claims-made professional, cyber, or other liability coverage.
- Territory and jurisdiction: verify where the event may happen and where a claim may be brought.
- Defense costs: determine whether legal expenses sit within or outside the limit.
- Contractual liability: identify liabilities assumed solely because the company signed a contract.
- Professional services: ordinary general liability may exclude losses arising from professional advice or services.
- Products and completed operations: confirm whether post-sale or completed-work liabilities are covered.
- Cyber and data: traditional liability forms may exclude or restrict electronic-data and privacy exposures.
- Pollution: environmental liability is frequently restricted and may need separate treatment.
- Subcontractors: establish whether subcontracted work creates covered or excluded exposure.
Three examples
Example 1: US-owned software subsidiary in Seoul
Assume a US company forms a Korean subsidiary with 20 employees and sells software services to Korean corporate clients. Its most important checks may include statutory industrial accident coverage, professional indemnity, cyber and privacy exposure, D&O coverage, and the insurance clauses in enterprise customer contracts.
Its physical premises risk may be modest compared with a factory, but a large professional-services or data incident could still dominate its liability profile.
Example 2: UK-owned consumer-goods importer
Assume a UK group establishes a Korean company that imports household products and distributes them through Korean retailers. Product liability becomes a central concern because the Korean entity participates in the supply chain. General liability for its warehouse or office, statutory workplace coverage, and any applicable vehicle insurance also need separate review.
The company should pay particular attention to product definitions, completed-operations wording, territorial scope, retailer indemnity clauses, and whether product recall is separately insured.
Example 3: Foreign company’s Korean branch
A Korean branch can create a different group-level exposure because it remains part of the foreign corporation rather than becoming a legally independent Korean subsidiary. The insurance review should therefore consider both the Korean branch and the overseas headquarters, including whether the global program responds to Korean claims and whether locally issued coverage is required.
Common mistakes to avoid
- Buying only general liability and assuming every risk is covered. Motor, workplace, privacy, professional, product, and mandatory facility insurance can sit outside it.
- Using the parent’s certificate without checking the Korean insured entity. The name on the policy matters.
- Confusing statutory minimum coverage with adequate commercial protection. Compliance and risk financing are related but different questions.
- Ignoring customer contract requirements until after signing. The promised limits or endorsements may be difficult or expensive to obtain later.
- Assuming every overseas policy can directly insure the Korean operation. Korean insurance law restricts contracting with non-authorized insurers except in specified circumstances.
- Forgetting to update insurers when the business changes. A new factory, new product, US export program, acquisition, larger data set, or major subcontract can materially alter the exposure.
A practical sequence for foreign-owned companies
A useful insurance review can be done in the following order:
- Confirm the Korean legal entity. Identify the subsidiary, branch, representative office, or other structure that actually conducts the activity.
- Map compulsory coverage. Check employees, company vehicles, regulated premises, personal-information thresholds, and industry-specific licenses.
- Read customer and lease contracts. Extract every insurance limit, certificate, indemnity, and additional-insured requirement.
- Map the uninsured loss scenarios. Consider bodily injury, property damage, defective products, professional mistakes, cyber incidents, management claims, and business interruption.
- Compare the Korean exposure with the parent company’s global program. Identify duplication, gaps, territorial restrictions, and local-policy requirements.
- Request comparable quotes. Use the same limits, deductibles, territorial assumptions, and requested extensions where possible.
- Compare wording, not just price. Exclusions and claim-trigger provisions can matter more than a modest premium difference.
For executives newly operating in Korea, communication with landlords, brokers, employees, and counterparties can also be smoother when local expectations are understood. See the site’s guides to Korean business communication and Korean business etiquette for additional operational context.
The bottom line
For a foreign-owned company in Korea, “Do we need liability insurance?” is too broad a question. The better sequence is: What Korean legal requirements apply to this entity, what losses could realistically reach the company or its overseas parent, and which policy actually responds to those losses?
A small professional-services subsidiary may focus on industrial accident coverage, professional indemnity, cyber, and D&O. A manufacturer may need product liability, employer-related coverage, property and business interruption, pollution review, and international product territory. A restaurant, hotel, warehouse, or other prescribed facility may have additional compulsory liability requirements.
Finally, multinational groups should review the relationship between Korean local policies and overseas master programs rather than assuming one automatically substitutes for the other. A Korean-licensed commercial insurance broker and, where legal interpretation is material, Korean counsel can help confirm the entity-specific requirements before the company relies on a policy or signs a contract requiring insurance.
This article provides general information rather than legal, tax, or insurance advice. Korean statutes, enforcement decrees, licensing conditions, policy forms, and individual company circumstances can change the applicable result. Legal and regulatory points in this article were reviewed on September 24, 2026.